A vehicle titled under an owner’s LLC may only be used for commuting, grocery shopping, and driving family members around. In that situation, a personal auto policy may be sufficient.
On the other hand, a vehicle titled in an individual’s name may be used every day for deliveries, traveling to job sites, transporting equipment, or other business activities. In that case, a personal auto policy may not provide the coverage you expect when an accident happens.
So how do you know whether you need personal auto insurance or commercial auto insurance?
Let’s take a closer look.
1. If a Vehicle Is Titled Under a Business, Does It Always Need Commercial Auto Insurance?
Not necessarily.
For example, a business owner may purchase a vehicle and title it under an LLC, but the vehicle is driven only by the owner and is primarily used for commuting, shopping, family transportation, and other personal activities.
Even though the LLC owns the vehicle, its actual use is essentially personal.
Depending on the insurance company, a personal auto policy may still be an option, and commercial auto insurance may not be necessary.
However, there is one important issue to keep in mind: insurance companies have different underwriting rules for vehicles titled under a business.
Some personal auto insurance companies may accept vehicles titled under an LLC or corporation under certain circumstances, while others require the vehicle to be titled in an individual's name.
That’s why you shouldn’t automatically assume that a company-owned vehicle must have commercial auto insurance. In some cases, commercial coverage could cost significantly more when it isn't necessary.
At the same time, you shouldn't assume that every personal insurance company will accept the vehicle simply because you only use it personally.
2. If a Vehicle Is Titled Personally, Is Personal Auto Insurance Always Enough?
No. How the vehicle is actually used matters.
A vehicle may be titled in your personal name but primarily used for business purposes, such as:
Making deliveries or transporting food
Frequently traveling to customers or job sites
Providing passenger transportation, such as Uber Black
In these situations, the vehicle's use may fall outside what a standard personal auto policy is designed to cover.
If you purchase a personal auto policy without properly disclosing significant business use, a claim related to that business activity could be denied or otherwise not covered under the policy.
And the biggest risk isn't always damage to your own vehicle.
If you cause an accident that seriously injures someone, medical expenses, lost income, legal expenses, and other liability claims can easily become far more expensive than repairing your own car.
3. When Do You Need Commercial Auto Insurance?
If a vehicle is regularly used as part of the day-to-day operation of a business, commercial auto insurance may be appropriate regardless of whether the vehicle is titled personally or under a company.
Common examples include:
Regular deliveries or transportation of goods
Frequently carrying business tools, equipment, or materials
Regularly traveling between customers, projects, or job sites
Using the vehicle for passenger transportation services such as Uber Black
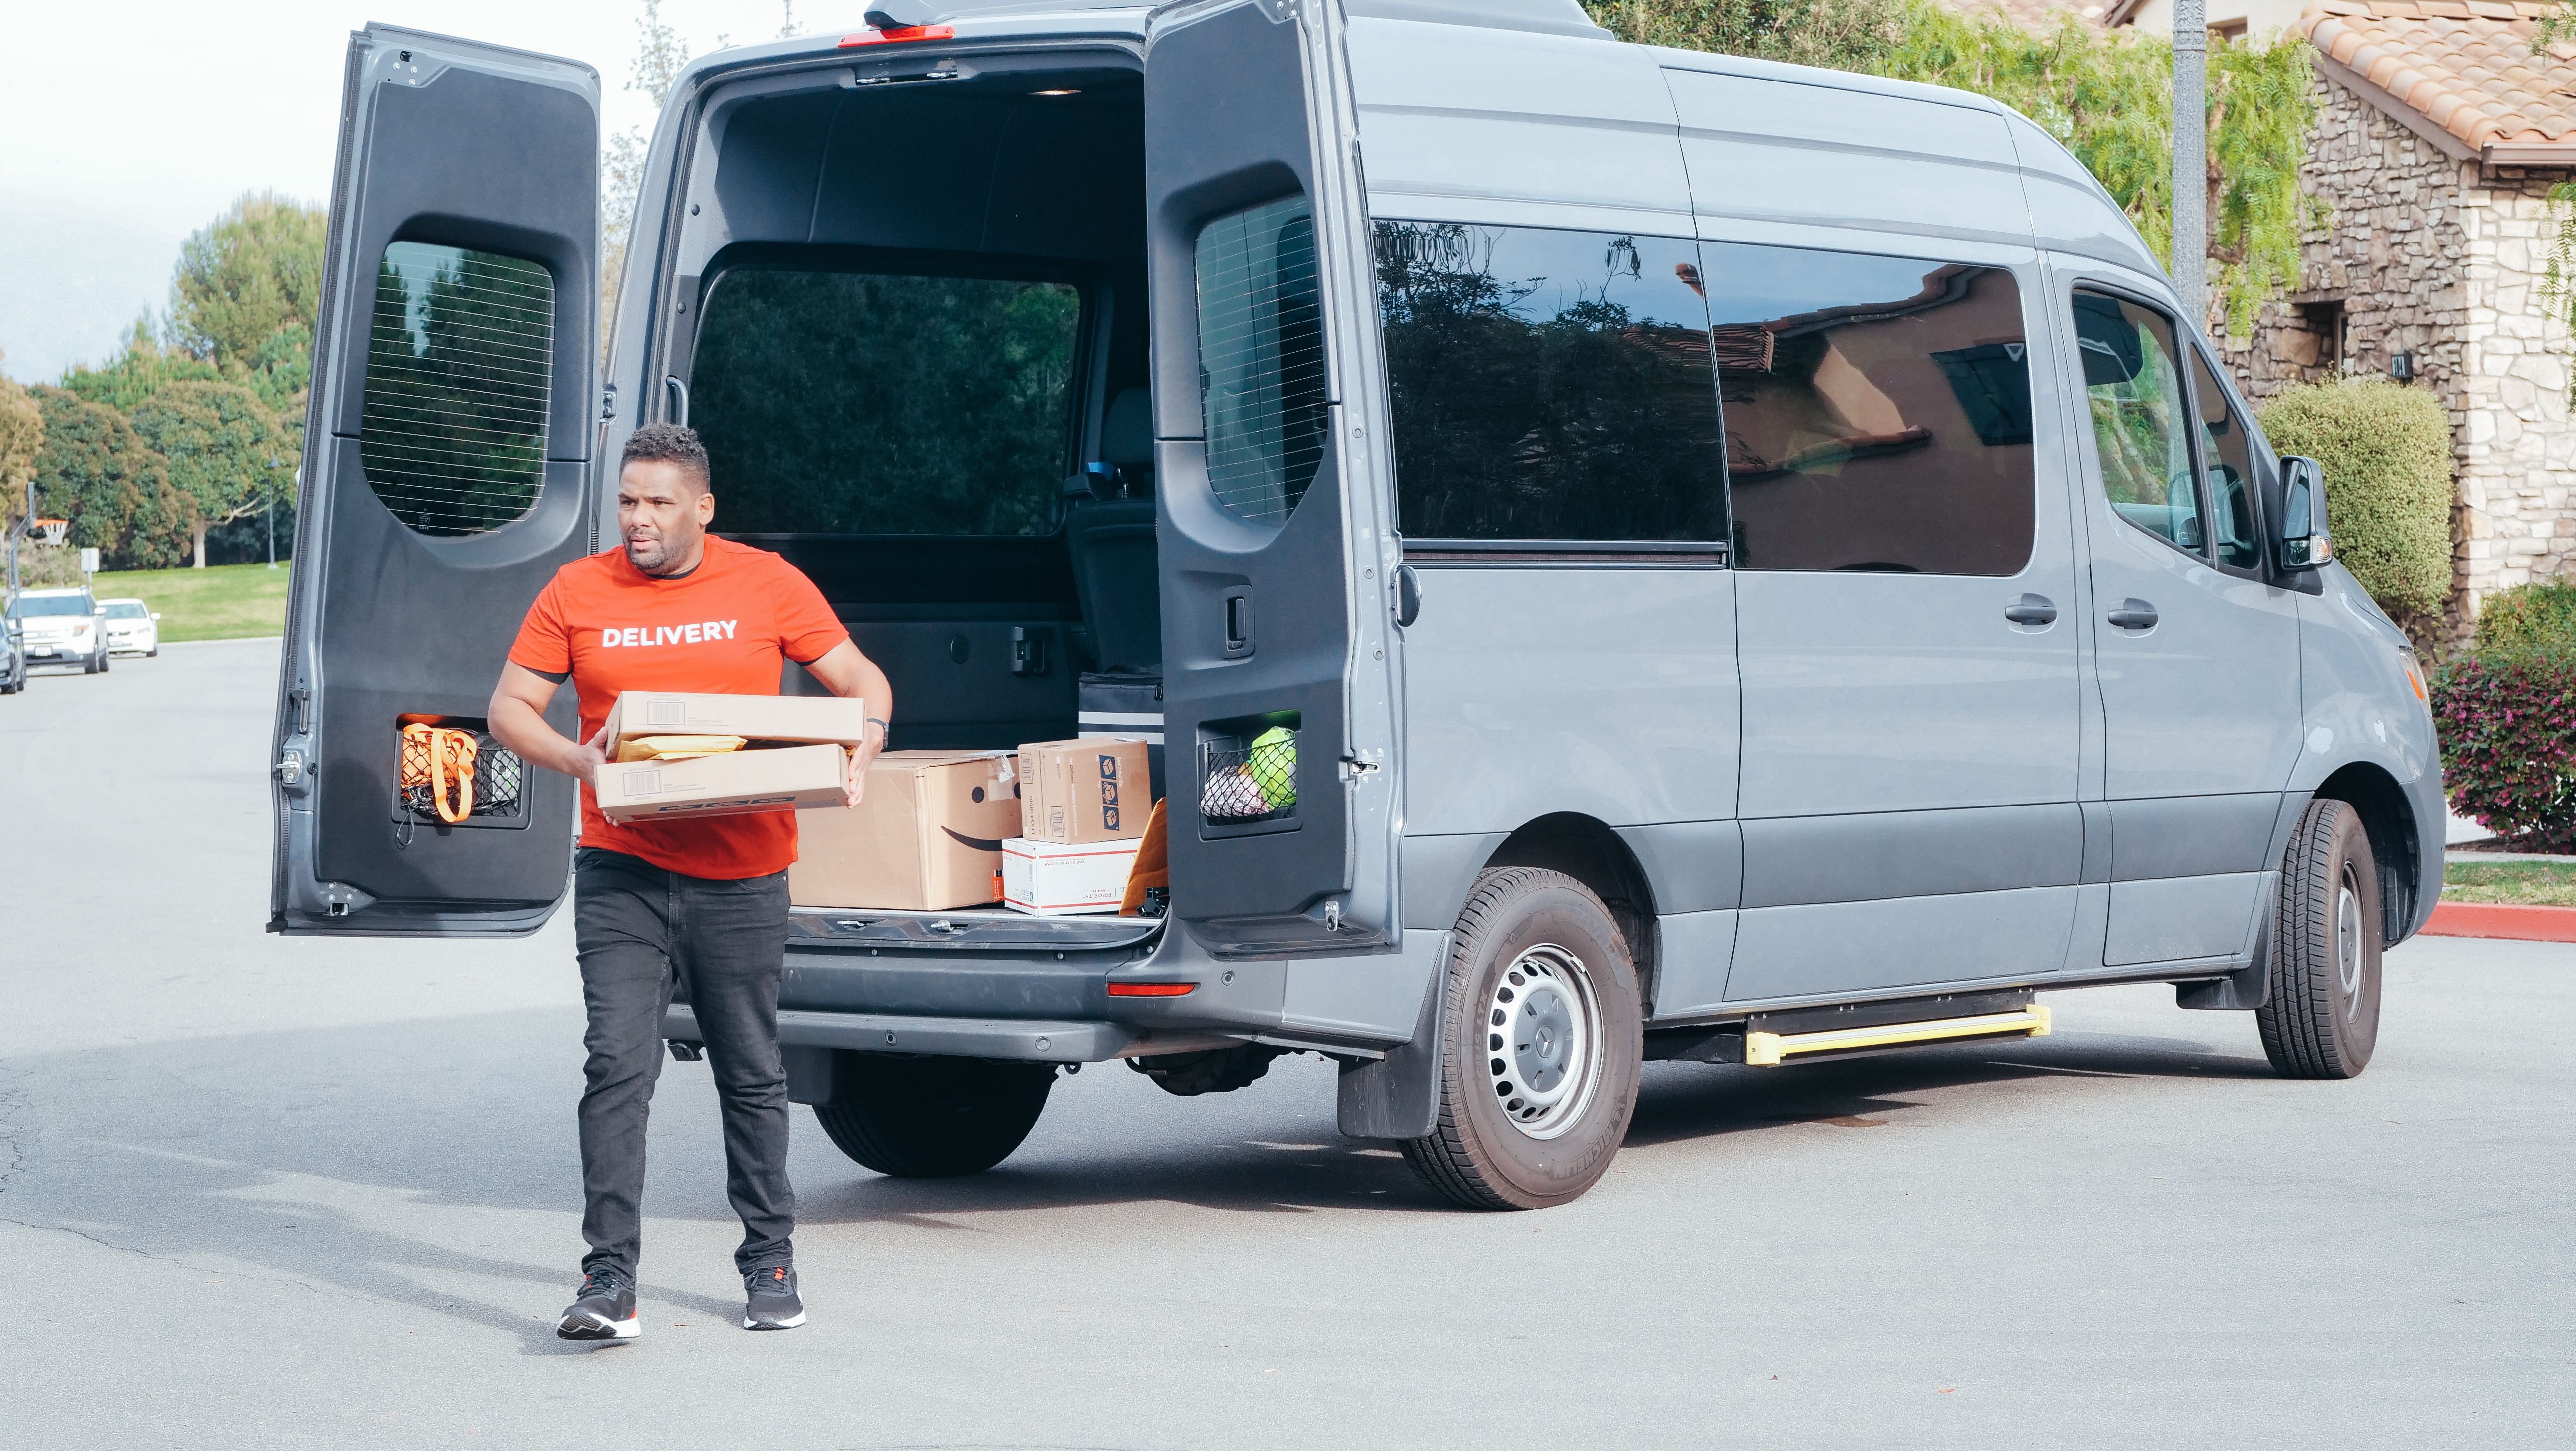
There are also situations where commercial auto insurance is generally much more likely to be necessary, including:
Employees regularly driving the vehicle for company business
Vehicles used in industries such as contracting, landscaping, delivery, or trucking
Vehicles whose type or configuration does not meet a personal auto insurer's underwriting requirements, such as certain cargo vans or commercial-use vehicles
4. Is Commercial Auto Insurance Cheaper Than Personal Auto Insurance?
Not necessarily.
Commercial and personal auto insurance are priced differently. Factors such as the type of vehicle, drivers, business industry, vehicle use, coverage limits, driving history, and claims history can all affect the premium.
In some situations, commercial auto insurance can be significantly more expensive. In others, the price may be similar to personal auto insurance—or commercial coverage may even be less expensive.
But there is one important rule to remember:
Don't choose between personal and commercial auto insurance based on price alone.
If a vehicle is being used for business purposes that aren't properly covered by a personal auto policy, choosing personal insurance simply because it's cheaper could leave you without the coverage you expected when an accident happens.
A better approach is:
Determine how the vehicle is actually used → Find out which insurance companies will accept that ownership and use → Compare coverage and pricing.
Not sure whether your vehicle should be insured under a personal or commercial auto policy?
Contact Zip Insurance. We can review how your vehicle is titled and used, help determine which type of policy may be appropriate, and compare available coverage and pricing for you.


